

Luxury Lending for High-Value Vehicle Owners
A luxury vehicle can represent far more than transportation or recreation. When cash is needed quickly for a business expense, real estate opportunity, tax bill, medical cost, or urgent repair, luxury lending can turn the equity in that asset into a practical source of funding. For qualified Florida owners, a high-value car, boat, or motorcycle may support access to $10,000 to $100,000 without the long wait and personal financial scrutiny of a traditional bank loan.
The difference is collateral. Rather than making a decision primarily on credit score, employment history, or a stack of tax returns, a specialty title lender looks closely at the market value of your vehicle and the equity available in it. That can make a major difference when time matters and conventional financing is moving too slowly.
What Is Luxury Lending?
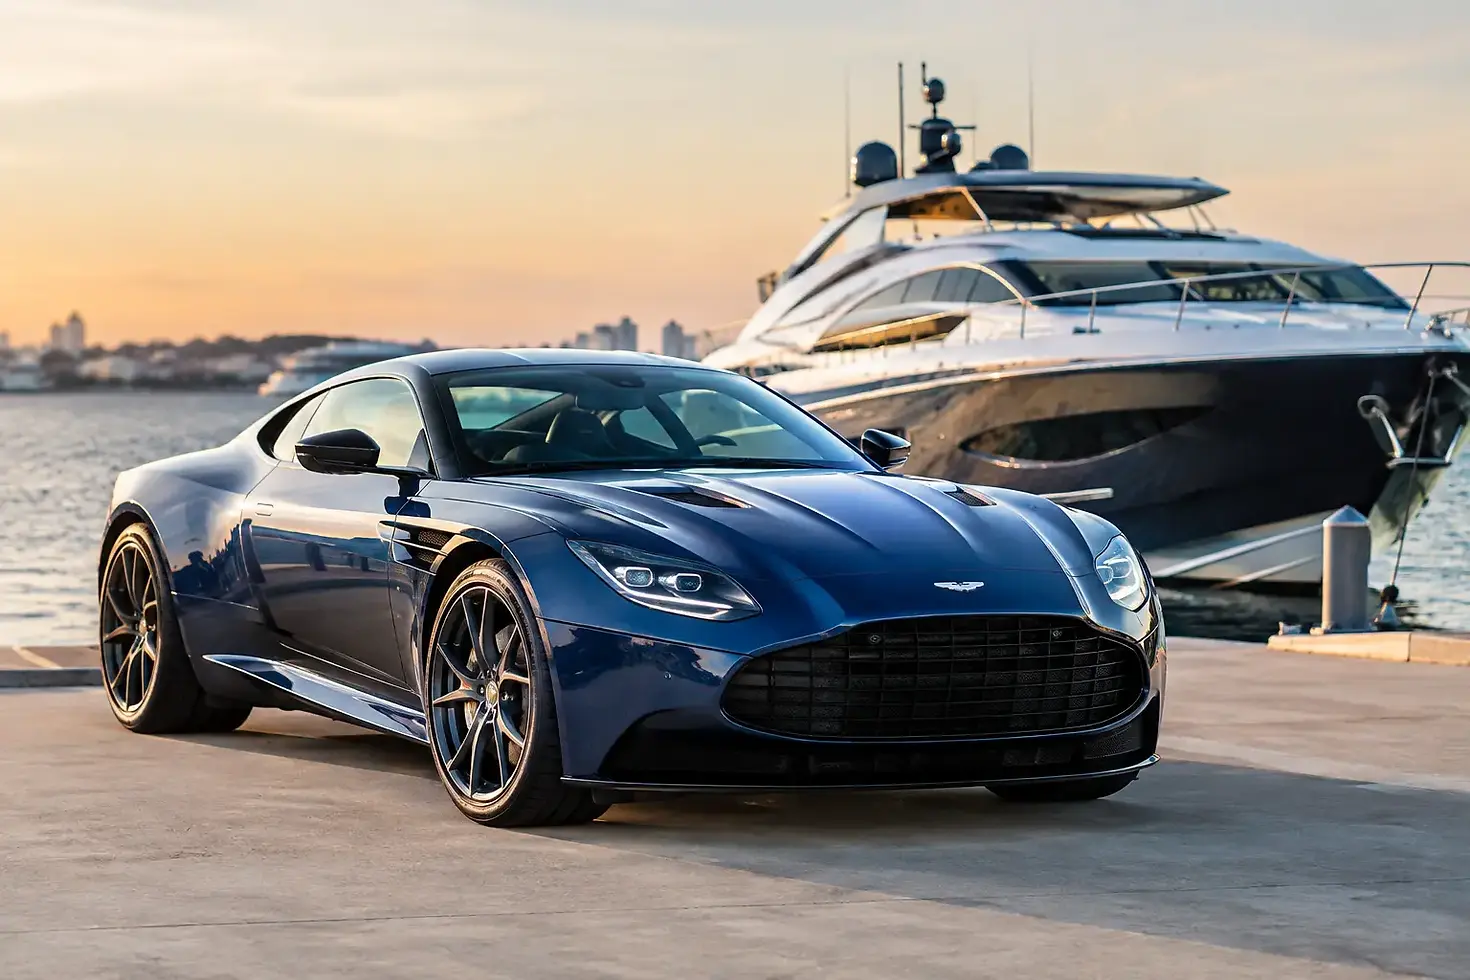
Luxury lending is asset-based financing designed for owners of high-value vehicles. It commonly includes exotic and luxury cars, premium SUVs, collector vehicles, yachts and boats, and high-end motorcycles. The vehicle title serves as collateral for the loan.
This is not the same as a small-dollar title loan built around a short emergency advance. With the right collateral, luxury lending can provide larger loan amounts and more flexible repayment options. The focus is on valuable assets that may not fit the lending limits of ordinary title loan providers.
For a borrower, the appeal is straightforward: your vehicle’s value may open a path to capital when a bank requires more documentation, takes weeks to make a decision, or declines an application based on credit. You are using an asset you already own to address a current financial need.
That does not mean every luxury vehicle will qualify for the same amount. The year, make, model, condition, mileage, ownership status, and current market demand all affect the lender’s evaluation. Existing liens also matter because available equity is a key part of the approval decision.
When a High-Value Title Loan Makes Sense
Luxury lending is often a fit for people who need speed and prefer not to expose every detail of their income, investments, or personal credit profile. A business owner may need bridge capital before receivables arrive. A homeowner may need funds for a time-sensitive repair. Someone purchasing inventory, covering a legal expense, or handling an unexpected family cost may not have the luxury of waiting for a bank committee.
It can also make sense when selling the asset would create a bigger problem than borrowing against it. Selling a boat, luxury car, or motorcycle quickly often means accepting less than its true value. A title-based loan may provide liquidity without forcing a rushed sale.
Still, the right choice depends on your repayment plan. This type of financing is best used with a clear reason for borrowing and a realistic path to repayment. Fast money is valuable when it solves a defined problem. It should not become an open-ended substitute for a long-term financial strategy.
How Luxury Lending Works
The process is designed to remove unnecessary delays. You provide basic information about the asset, including the title and vehicle details. The lender reviews the collateral, confirms ownership and evaluates its market value. If the asset and available equity support the request, loan terms are presented for review.
At Miami Boat & Auto Pawn, qualifying borrowers can pursue same-day title loans from $10,000 to $100,000 on high-value cars, boats, and motorcycles. There is no credit check and no employment-based underwriting requirement. That matters for applicants whose credit profile does not tell the full story or whose income is structured outside a traditional paycheck.
Approval speed does not remove the need to read the agreement carefully. Before signing, make sure you understand the loan amount, repayment schedule, interest and applicable charges, the length of the term, and what happens if a payment is late. A reputable lender should answer those questions directly, not bury the details in vague language.
Repayment periods can range from 30 days up to 10 years depending on the loan structure and qualification. A shorter term may reduce the total cost of borrowing but create a higher payment. A longer term may lower the payment amount while increasing the total amount repaid over time. The best option is the one that fits your actual cash flow, not simply the lowest monthly payment.
Why Traditional Banks Can Be the Wrong Tool
Banks work well for some borrowers and some timelines. If you have strong credit, predictable income, complete financial records, and no immediate deadline, a conventional loan may be worth considering. The trade-off is process. Banks typically review credit, debt-to-income ratios, income verification, account history, and supporting documents. Their approval timeline may not match an urgent situation.
Luxury lending approaches the question differently. Instead of asking whether your financial profile fits a standard lending box, it starts with the marketable value of the collateral. This can be especially helpful for entrepreneurs, independent contractors, investors, retirees with valuable assets, and borrowers recovering from credit challenges.
Privacy is another consideration. Many people do not want to explain a temporary cash need to a bank, provide extensive business records, or wait for an underwriter to review every account. A vehicle title loan can be a more direct conversation: here is the asset, here is the value, and here is the amount needed.
The trade-off is that the vehicle title secures the loan. If you do not meet the repayment obligation, the asset is at risk. That is why the loan amount should be based on need and repayment ability, not simply the maximum available equity.
What to Check Before You Borrow
A fast approval should still come with a careful decision. Start by confirming that the lender clearly explains all terms. Transparent lending means you know what you are agreeing to before funds are issued.
Ask whether there are hidden fees, whether early payoff is allowed, and whether there are prepayment penalties. If you expect to pay the loan off ahead of schedule, that answer can affect your total cost. Also ask how payments are scheduled and what support is available if you have a question during the loan term.
Next, be honest about the reason for the funds. If the loan will protect a business opportunity, prevent a costly disruption, or bridge a short-term gap with a known repayment source, it may be a sensible use of collateral. If repayment is uncertain, consider whether a smaller amount or different term would create less pressure.
Finally, protect yourself from rushed assumptions. “No credit check” does not mean “no responsibility.” It means the collateral plays a central role in approval. Your obligation to make payments remains real, and the agreement deserves your full attention.
Luxury Lending for South Florida Owners
Miami, Dade County, Broward County, and Ft. Lauderdale are full of owners whose vehicles carry meaningful value. A luxury SUV, sports car, performance motorcycle, or boat can be a substantial asset, yet many lenders are not equipped to evaluate it properly. Generic lenders may overlook specialized features, collector demand, marine value, or the equity that makes a larger loan possible.
A specialty lender understands that a high-value title requires a different conversation. The goal is not to force a luxury asset into a small-dollar lending model. It is to evaluate the asset fairly and provide a clear funding option for borrowers who need capital now.
If your vehicle has equity and you need funds quickly, start with the numbers: what you need, what you can comfortably repay, and what the title is worth in the current market. A clear plan turns a valuable asset into a financial option instead of a financial burden.


Comments